Article URL: https://everydaywerk.com/laid-off-cut-expenses/
Yesterday Was About the Layoff. Today, I Made a List.
- PROTECT
- STABILIZE
- EARN
- PIVOT
- BUILD
- CHOOSE
This article is part of The Exit Plan, Everyday Werk’s practical framework for protecting yourself and what you’ve built, stabilizing your finances, creating income and deciding what comes next when work—or life—changes.
Yesterday, I got laid off.
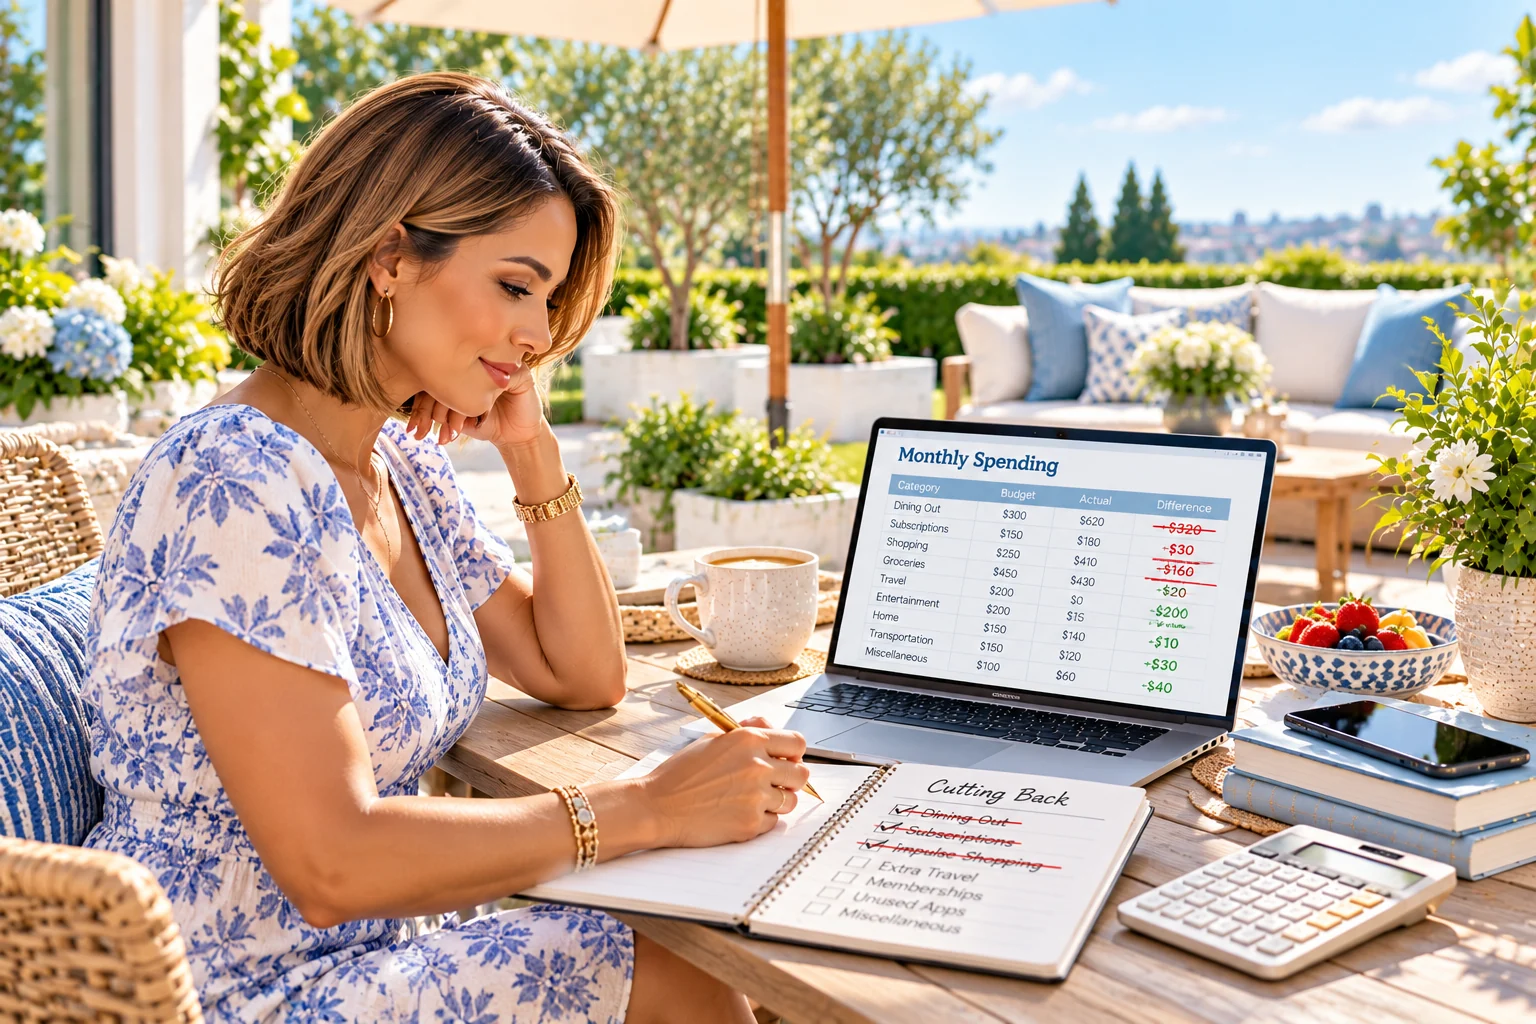
Today, I started making a list.
Not a sophisticated financial plan. Not a perfectly organized spreadsheet projecting every dollar I might need for the next 12 months.
Just a list.
WHAT AM I PAYING FOR EVERY MONTH THAT I CAN STOP, PAUSE, DOWNGRADE OR REDUCE—RIGHT NOW?
Because there were plenty of bigger questions I still needed to figure out.
What happens with health insurance? How long will my severance last? When should I file for unemployment? How long could this job search take? What expenses absolutely have to stay?
Those questions mattered.
But on Day Two, there was something much simpler I could do.
I COULD STOP SOME OF THE UNNECESSARY MONEY FROM LEAVING MY ACCOUNT.
So I got busy.
Subscriptions I wasn't really using? On the list.
Services I could downgrade? On the list.
Recurring charges I'd barely noticed? Definitely on the list.
Things I'd been paying for mostly because I'd never taken the time to cancel them?
You already know.
ON. THE. LIST.
None of those changes was going to replace my paycheck. Canceling a handful of subscriptions wasn't going to solve every financial challenge that could come with losing my job.
That wasn't the point.
The point was to grab some of the LOW-HANGING FRUIT while I figured out the bigger stuff.
A few dollars here. $30 there. Maybe $100 somewhere else.
Every recurring expense I eliminated was money that didn't have to come out of my account next month—or the month after that.
And on Day Two, that felt like progress.
THE QUICK TAKE: Don't Try to Solve Everything Today
If you've just been laid off, your financial to-do list can get overwhelming very quickly.
So we're not tackling the whole thing today.
Instead, give yourself 20 or 30 minutes and answer one question:
WHAT CAN I STOP PAYING FOR—OR PAY LESS FOR—WITHOUT CREATING ANOTHER PROBLEM FOR MYSELF?
That's it.
We're looking for expenses that can be addressed relatively quickly. Things you can cancel with a few clicks. Services you can pause. Plans you can downgrade. Bills where a phone call might uncover a less expensive option.
START WITH THE EASY STUFF.
We'll deal with the bigger stuff separately.
Table of Contents
- Step 1: Go Subscription Hunting
- Step 2: Give Every Expense an Action
- Step 3: Where I Started Looking
- Step 4: What You Paid For Because of Your Job
- Step 5: When a New Expense Makes Sense
- Step 6: Find the Annual Charges
- Step 7: Don't Cut Yourself Into Another Problem
- Step 8: Add Up What You Stopped
- Free Day Two Expense-Cutting WERKsheet
- Frequently Asked Questions
Step 1: Go Subscription Hunting
This is where I started.
Subscriptions have a sneaky way of accumulating.
$5.99 here. $14.99 there. $29.99 for something you signed up for months ago and completely forgot about.
Individually, they may not look particularly threatening. Collectively, they can quietly claim a meaningful chunk of your money every month.
And don't think only about streaming services.
Look for streaming TV and music, premium apps, software, cloud storage, news and magazine subscriptions, fitness apps and gym memberships, meal or grocery delivery memberships, automatic product shipments, beauty subscriptions, gaming subscriptions, professional tools, membership clubs and anything else that has been quietly renewing because you never got around to canceling it.
That $6.99 subscription isn't going to save your financial life.
BUT NEITHER DOES IT NEED TO KEEP CHARGING YOUR CREDIT CARD UNTIL 2028.
MAKE IT WERK
Don't Rely on Your Memory. Follow the Money.
Pull up the last 60 to 90 days of transactions from your checking accounts and credit cards.
Scan them line by line.
You're looking for anything recurring—and particularly anything that makes you say:
“Wait. I'm still paying for that?”
Write it down.
Don't decide what to do with everything yet. Right now, we're simply finding the money.
Step 2: Give Every Expense an Action
CANCEL IT — You're not using it. You forgot you had it. Or it simply isn't important enough to keep paying for while your income is uncertain. Cancel it—and actually finish the cancellation.
PAUSE IT — Maybe you genuinely enjoy the service and want it back later. See whether the company offers a pause, vacation or temporary suspension option.
DOWNGRADE IT — You need the service—but do you need that version of the service? Look at your phone plan, internet speed, streaming package, cloud-storage tier, software subscriptions and other services with multiple levels.
CALL ABOUT IT — Before canceling something you actually need, ask whether you can pay less for it. There may be another plan, a current promotion or a different option that isn't obvious from your account dashboard.
Don't Know What to Say?
You don't need to give a company your entire life story.
“I've recently had a change in employment and I'm reviewing my monthly expenses. Before I cancel this service, I'd like to know whether there's a lower-cost plan, current promotion or temporary option available for my account.”
Then stop talking and let them tell you what's available.
If the first option isn't particularly helpful, ask: “Is that the lowest-cost option currently available to me?”
You may get a discount. You may discover a cheaper plan. You may get absolutely nothing. But you'll know you checked.
Step 3: Here's Where I Started Looking
Once I started, I realized this wasn't just about canceling a few streaming services.
I began going category by category through the things I paid for regularly and asking:
DO I STILL NEED THIS? AM I USING WHAT I'M PAYING FOR? IS THERE A LESS EXPENSIVE WAY TO GET IT? AND AM I ALREADY PAYING FOR THIS BENEFIT SOMEWHERE ELSE?
If you're staring at your own blank piece of paper wondering where to begin, here are some places to look.
Cable, Internet and Entertainment
I looked at my cable provider and the package I was paying for.
Was I watching enough of what I was paying for? Was there another provider or plan that made more sense? Could I change how I received television service without giving up the things I actually watched?
This wasn't necessarily about eliminating entertainment. It was about stopping myself from paying more than I needed to for it.
Do the same with internet service. Are you paying for a speed tier or package that made sense when you selected it but doesn't match your current usage?
Before changing anything, understand the new price, equipment costs, contract terms and promotional period so today's savings don't become tomorrow's surprise bill.
Cell Phone Plans: Look Beyond the Monthly Price
I also looked at cell phone plans and providers.
But don't compare wireless plans based only on the number printed next to “monthly price.” Look at what comes with the plan.
Some wireless providers include or discount entertainment and other benefits on qualifying plans. If something you're already paying for separately is included, that could potentially eliminate another bill.
The important calculation is your total household cost, not whether something has the word “free” next to it.
MAKE IT WERK
Hunt for Duplicate Benefits
Before paying separately for a streaming service or other subscription, check whether you already have access to it through another service you pay for.
Look at your wireless plan, internet package, credit-card benefits, memberships and other services.
But do the math before switching providers solely for a perk.
A “free” $10 subscription isn't saving you anything if you move to a plan that costs $25 more each month.
Utilities: Sometimes Predictability Has Value, Too
I also looked at my utilities.
Saving money wasn't my only concern. PREDICTABILITY MATTERED.
When income becomes uncertain, knowing approximately what will leave your account every month can make planning easier.
So I looked at stable or budget-billing options that could make monthly utility expenses more predictable.
WERK NOTE
Predictable Doesn't Necessarily Mean Cheaper
A level or budget-payment program may smooth seasonal fluctuations without reducing your total utility costs.
Understand how your provider calculates the payment, how often it adjusts and how any difference between estimated and actual usage is handled.
The benefit may be cash-flow predictability, not an actual discount.
Apps, Software and All Those Random Subscriptions
Then came everything else: apps, software, storage, memberships, and services I'd subscribed to for a particular reason months—or years—earlier.
Instead of automatically canceling everything, I started asking: AM I ON THE RIGHT PLAN FOR HOW I ACTUALLY USE THIS NOW?
Sometimes the answer was to cancel. Sometimes it was to downgrade. Sometimes there was a cheaper option. And sometimes I decided the service was worth exactly what I was paying.
The important thing was this: I KNEW I WAS PAYING FOR IT—AND WHY.
Step 4: What Were You Paying for Because of Your Job?
This is an easy category to miss.
Your old work life may have created expenses that don't make as much sense now.
Maybe you personally paid for professional software, industry publications, networking memberships, AI tools, cloud storage, design tools, productivity apps, professional organizations, courses, commuting services, parking or other things you justified because they supported the job you had.
Your circumstances have changed. YOUR SUBSCRIPTIONS MAY NEED TO CHANGE WITH THEM.
Ask yourself: WOULD I SUBSCRIBE TO THIS TODAY, GIVEN WHAT I'M DOING TODAY?
If the answer is no, it belongs on the list.
Step 5: But Your New Situation May Require a New Expense
Here's the other side of that conversation.
You may discover that something you didn't need while you were employed becomes useful now.
Maybe that's a paid job-search tool. Maybe it's professional training. Maybe it's a networking membership. Maybe it's software you need to launch a consulting business.
For example, you may decide that the additional job-search and networking features available through a paid LinkedIn plan are useful during an active search.
That doesn't necessarily mean piling a new subscription on top of everything else.
Ask: WHAT CAN I ELIMINATE TO MAKE ROOM FOR SOMETHING THAT MATTERS MORE RIGHT NOW?
If you stop paying $30 for something that no longer serves you and redirect that $30 toward a tool that supports your current goal, you haven't increased your monthly spending. You've REDIRECTED IT.
WERK TIP
Your Budget Should Change When Your Priorities Change
Don't look only for things to eliminate. Look for dollars you can REASSIGN.
Something that made perfect sense six months ago may not deserve your money today. Something you didn't need six months ago may now be worth paying for.
The question becomes: “Given where I am right now, is this where I want this dollar to go?”
Step 6: Find the Annual Charges Before They Find You
Monthly charges are relatively easy to spot. Annual renewals can be sneakier.
A service you haven't thought about in months can suddenly hit your credit card for $99, $149 or $299.
Search your email for terms such as renewal, subscription, membership, annual plan, your plan renews and upcoming payment.
Look at last year's credit-card statements, too. Then add upcoming renewals to your list.
WERK NOTE
Turning Off Auto-Renew May Be Enough
For some prepaid subscriptions, turning off automatic renewal simply prevents the next charge while allowing you to continue using the service through the period you've already purchased.
Check the terms before canceling so you understand what happens to the time you've already paid for.
Step 7: Don't Cut Yourself Into Another Problem
When your income suddenly changes, there's a temptation to look at every bill as the enemy. It isn't.
Some expenses are protecting you. Some keep your household functioning. Some may be important to your health, transportation, job search or ability to earn your next dollar.
Before canceling something, ask: WHAT HAPPENS IF I DON'T HAVE THIS?
Be particularly thoughtful about insurance coverage, medications and healthcare, essential utilities, housing obligations, transportation, minimum debt obligations, security services and professional tools you genuinely need.
Even with seemingly optional services, understand the consequences before you cancel. You don't want to save $30 today only to create a $300 problem next month.
This isn't about cutting your household down to nothing. It's about identifying expenses you can change relatively easily while preserving the things you need.
Step 8: Add Up What You Stopped
This is the part I found motivating.
Don't just cancel something and move on. WRITE DOWN WHAT YOU SAVED.
For example, if you eliminated a $22.99 streaming service, downgraded internet from $110 to $80, canceled a $9.99 app and paused a $49 gym membership, you'd keep $111.98 from leaving your account each month.
If those changes remained in place for 12 months, that's $1,343.76.
Did you replace your paycheck? Of course not. But that's not what we're doing today.
You found more than $100 a month that can stay in your household while you figure out what comes next. THAT'S A WIN.
Every recurring expense you sustainably reduce can also lower the amount your household needs to cover each month. Later, when you calculate your Cash Gap, those changes may mean there is less gap to fill.
And when less money needs to leave your household each month, your available resources may last longer. That’s one of the reasons this simple Day Two exercise can matter to your Financial Runway.
Note: figures above are illustrative examples.
SUPER WERKER CHALLENGE
How Much Can You Stop in 30 Minutes?
Set a timer. Seriously.
Give yourself 30 minutes and see what you can find.
Spend the first 10 minutes reviewing checking and credit-card transactions.
Spend the next 10 canceling or pausing the obvious expenses.
Use the final 10 to downgrade what you can and make a list of the companies you need to call.
Then calculate your new monthly savings.
We're not trying to build the perfect budget in 30 minutes. We're seeing how many unnecessary dollars we can stop from walking out the door.
The Day Two Expense-Cutting WERKsheet
EVERYDAY WERK FREE RESOURCE
I created a simple tool around the same idea I used for myself: MAKE THE LIST AND GET BUSY.
The Day Two Expense-Cutting WERKsheet helps you identify expenses across your life, record what you're paying, decide what you're going to do and see how much you've actually changed.
For each expense, choose: CANCEL · PAUSE · DOWNGRADE · CALL · KEEP · REDIRECT.
Then record the old cost, new cost, monthly savings, annualized impact and—most importantly—whether you've actually completed the action.
Because identifying a $40 expense doesn't save you $40. DOING SOMETHING ABOUT IT DOES.
The WERKsheet also includes an Expense Hunt to help you look across categories such as phone, internet, streaming, utilities, apps, software, work-related expenses, shopping memberships, fitness, home services and other recurring charges.
And there's one more field: WHY AM I KEEPING THIS?
Maybe the answer is: I use it every day. It's included with another service. I need it for my job search. It protects my family. It saves me more than it costs. It brings me joy and I can afford it.
Those are perfectly legitimate answers.
The point isn't to cancel everything. THE POINT IS TO KNOW.
And Day Two Was Only the Beginning
I did the obvious things on Day Two. But I didn't finish on Day Two.
Once I started paying attention, the practice continued.
Day after day, I noticed other expenses. I reconsidered plans. I compared providers. I found subscriptions I'd overlooked. I thought differently about new recurring commitments.
And I'm still doing it.
The goal wasn't to spend as little money as humanly possible.
It was to get to a place where I could look at the recurring expenses in my life and say:
I KNOW WHAT I'M PAYING FOR. I KNOW HOW MUCH IT COSTS. AND I KNOW WHY I'M KEEPING IT.
That's the habit I carried forward from Day Two.
What I Didn't Try to Do on Day Two
I didn't try to solve my entire financial future in one sitting. And I don't think you need to, either.
There are bigger post-layoff financial questions that deserve their own time and attention: severance, unemployment benefits, health insurance, retirement accounts, taxes, debt, emergency savings, your new household budget, and how long your available money needs to last.
Those aren't unimportant. THEY'RE TOO IMPORTANT TO SQUEEZE INTO A QUICK EXPENSE-CUTTING EXERCISE.
This is simply one of the first things I did because it was something I could control immediately.
WERK NOTE
This Is Financial Triage, Not the Whole Financial Plan
This exercise won't stop every financial consequence of losing your job. It isn't designed to.
Today we're looking for some of the easiest expenses to stop, pause, downgrade, redirect or reduce while you begin working through the bigger financial decisions ahead.
Depending on your circumstances, those larger decisions may be worth discussing with an appropriately qualified financial, tax, insurance or benefits professional.
One More Thing: Don't Make Misery Your Budget
There's another side to cutting expenses that we don't talk about enough.
You just got laid off. You don't necessarily need to respond by stripping every enjoyable thing out of your life.
If your favorite streaming service lets you curl up on the couch and decompress at the end of a very strange week—and you can afford to keep it—maybe that isn't the first subscription we need to find.
The goal is not punishment. The goal is INTENTIONAL SPENDING.
Keep what matters. Question what doesn't. Redirect money when your priorities change. And stop paying for things you don't even care about anymore.
Start With the List
If you're reading this on your Day Two—or Day Five, Day 20 or whenever you've finally had a chance to look at your finances—start small.
Open your bank statement. Open your credit-card statement. Grab a piece of paper, your notes app or the Day Two WERKsheet.
And start making your list.
CANCEL IT. PAUSE IT. DOWNGRADE IT. CALL ABOUT IT. KEEP IT. REDIRECT IT.
Then add up what changed.
You won't solve everything today. Neither did I.
But you can stop some money from leaving your account while you work on what comes next.
And sometimes, when so much suddenly feels outside of your control, doing the things you can control is a pretty good place to start.
Frequently Asked Questions
What expenses should I cut first after a layoff?
Start with expenses that are relatively easy to change without disrupting necessities: unused subscriptions, memberships, duplicate services, premium upgrades and discretionary recurring charges. The right choices depend on your household and circumstances.
Should I cancel every subscription after losing my job?
No. Review each expense based on cost, how much you use it and what giving it up would actually accomplish. The purpose is to eliminate or reduce spending that isn't serving you—not to automatically cancel everything enjoyable.
How far back should I review my statements?
Starting with the previous 60 to 90 days can reveal many recurring monthly charges. Looking back approximately a year can also help uncover annual renewals that won't appear during a shorter review.
Should I switch my cell phone, internet or cable provider?
Maybe—but compare the entire cost before switching. Consider the plan price, taxes and fees, equipment, introductory pricing, contract terms and benefits you would gain or lose. A bundled perk only saves money if the total arrangement costs less or provides greater value for something you would otherwise purchase.
Can a utility budget-billing plan lower my bills?
Not necessarily. These programs generally focus on making monthly payments more predictable by smoothing fluctuations rather than reducing your underlying usage or total cost. Review your utility provider's specific terms.
What if I need to add a new subscription for my job search?
Treat it as a new priority rather than automatically adding another expense. Ask whether something you're currently paying for can be canceled, downgraded or redirected to make room for the new tool.
Is this enough financial planning after a layoff?
No—and it isn't intended to be. This is a quick expense-cutting exercise focused on relatively easy opportunities to reduce or redirect recurring spending. Decisions involving severance, unemployment, health coverage, retirement accounts, taxes, debt and longer-term cash flow deserve separate consideration.