Article URL: https://everydaywerk.com/ibotta-review/
Quick Take
After more than a decade using Ibotta and earning over $1,600 in cash back, it's still one of my go-to apps when I want to recover some of the money I'm already spending.
It requires more planning than an app where you simply scan every receipt. But when the offers match your shopping list, that little bit of effort can be worthwhile.
My two biggest cautions? Understand the $20 withdrawal threshold, and don't let your earnings sit indefinitely without paying attention to Ibotta's inactivity policy.
My strategy: Plan what I need. Check the offers. Shop normally. Cash out when eligible. Give the money a job.
Ibotta Quick Facts
| Best for | Shoppers who want actual cash back and don't mind a little planning |
| Cost | Free |
| Available on | iPhone, Android and web |
| Minimum withdrawal | $20, subject to additional eligibility requirements |
| Withdrawal options | Eligible bank accounts, PayPal and digital gift cards |
| My experience | Member since November 2015; more than $1,600 in lifetime earnings |
Download Ibotta: Official website · Apple App Store · Google Play
Table of Contents
We Say We Don't Have Money. But Somehow, We're Still Spending It.
You can be trying to save money, pay down debt, recover from a job loss or simply stretch your paycheck a little further—and still have to buy groceries.
The car still needs gas.
The house still needs toilet paper.
Somebody needs detergent.
And dinner still has to happen.
That's one reason I've continued using Ibotta for more than a decade.
I'm not interested in spending $8 on something I don't need because an app offers me $2 back. That's not saving money.
My philosophy is simpler:
If the money has to leave my wallet anyway, I want that spend to WERK as hard as possible before it goes.
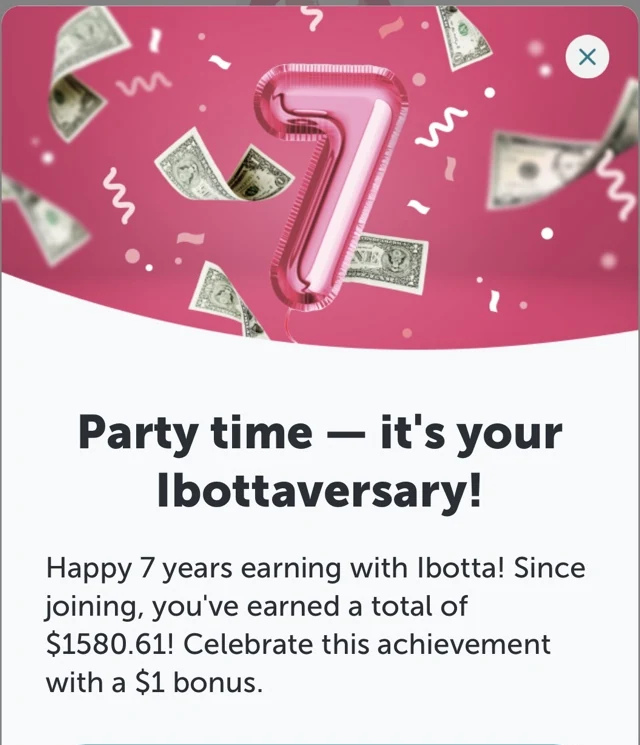
I joined Ibotta on November 26, 2015. Since then, I've earned more than $1,600 in cash back from purchases I was already making.
Not overnight. Not without effort. And definitely not because every receipt produced some spectacular rebate.
But over time? Those dollars added up.
What Is Ibotta?
Ibotta is a free cash-back app that rewards eligible purchases from participating retailers and brands.
For many in-store offers, you select the products you intend to buy, purchase the qualifying items and submit your receipt. Depending on the retailer, you may also be able to link a loyalty account. Ibotta offers online shopping opportunities, too.
One distinction matters to me: Ibotta pays cash back, not just points.
Once you meet its withdrawal requirements, you can choose from available options that include PayPal, an eligible bank account and digital gift cards.
A gift card can certainly be useful. But money I can transfer to my bank account gives me more flexibility.
How I Make Ibotta Part of My Shopping Routine
The biggest mistake I see people make with Ibotta is thinking the process starts after they shop.
For me, it starts before I leave home.
When I'm making my grocery list, I check Ibotta. I look for offers on things I already intend to buy, then decide whether any of them make financial sense.
My routine is simple:
Plan → Check offers → Shop → Redeem → Cash out.
Brand Loyal? Search Your Brand. Flexible? Search What You Need.
If I know exactly which coffee, yogurt or household product I want, an Ibotta offer is a bonus—not a reason to change my shopping plans.
But there are products where I'm flexible.
Maybe I don't care which brand of butter I buy this week. I just need butter.
That's when I'll compare the available offers and the actual shelf prices.
A $2 rebate doesn't make a $7 product a bargain if I would have happily bought a comparable product for $3.
MAKE IT WERK
Add Ibotta to your grocery-list ritual. Spend a few minutes checking offers before you leave home, and let your shopping list—not the app—determine what goes into your cart.
Can You Combine Ibotta With Coupons and Other Discounts?
This is one area where longtime users need to pay attention because the rules have changed.
I remember being able to combine manufacturer and store coupons with Ibotta offers more freely in the past. Today, you can't assume every coupon and offer will stack.
For example, Ibotta says paper and digital manufacturer coupons cannot be combined with an Ibotta offer on the same product at Walmart or Dollar General. Other retailers and individual offers can have different restrictions.
That doesn't mean you should stop looking for opportunities to maximize a purchase.
Store sales and eligible discounts can still improve the overall deal. Just check the current offer terms before buying.
MAXIMIZE IT
Don't judge the deal by the rebate alone. Compare the final price after all eligible discounts and cash back. The biggest-looking offer isn't necessarily the biggest saving.
Forgot to Check Before Shopping? Check Anyway.
Ideally, I look at Ibotta before I shop.
Real life doesn't always cooperate.
If I get home with a receipt and realize I forgot to check, I still open the app. For qualifying receipt submissions, Ibotta may let you add eligible offers during the receipt-confirmation process. Receipt submissions generally have a seven-day purchase window, although retailer-specific procedures vary.
So don't automatically throw that receipt away.
Check first.
I still prefer planning ahead because it gives me more control and reduces the chance of missing an offer.
Don't Forget About Online Shopping
Ibotta isn't limited to the grocery aisle.
It also offers cash-back opportunities with participating online retailers.
My rule is the same online as it is in-store: start with the purchase I already intended to make.
If I'm planning to order something anyway, I'll check whether going through Ibotta creates an opportunity to earn cash back.
I don't manufacture an online purchase just because a rebate exists.
Cash back should improve a purchase—not create one.
How Fast Can You Actually Get Your Money?
“Earn cash back” doesn't tell me when that money becomes useful.
When I'm evaluating an app, I want to understand the entire process.
With Ibotta, I think about three separate clocks.
Clock 1: Purchase to Cash Back
Eligible in-store purchases often post relatively quickly, but processing times depend on the retailer and redemption method.
In my experience, I've sometimes seen earnings appear in about a day. That's encouraging, but I wouldn't plan an important bill payment around my fastest redemption.
Clock 2: Earnings to the $20 Threshold
You need at least $20 in eligible earnings before you can withdraw. New users must also meet additional requirements, including successfully redeeming an offer and completing the initial waiting period.
This can be the bigger hurdle.
If your balance is $18 and you earn another $4, you may reach the threshold relatively quickly.
If you're starting from zero and the available offers don't match what you need, reaching $20 could take considerably longer.
That's why “How quickly does Ibotta process a withdrawal?” and “How quickly can I earn $20?” are two very different questions.
Clock 3: Withdrawal to Usable Money
Once you're eligible to withdraw, the timing depends on the method you choose.
PayPal may be relatively quick, while bank transfers can take several business days. Digital gift cards are another option, with availability and minimums varying by retailer.
The complete journey is what matters:
Earn → Reach $20 → Withdraw → Use.
Why I Don't Wait Until I Need the Money
There have been periods when saving money was my goal.
And there have been periods when finding additional usable cash was my goal.
Those are different circumstances.
If I need to close a small cash gap, an app that might eventually produce a reward six months from now has a different job from one that could provide usable cash sooner.
That's one reason I pay closer attention to Ibotta when I'm deliberately trying to generate cash back.
But I don't think the best time to learn a rewards app is when you're desperate for another $20.
Learn how it works while things are relatively normal.
Find out which apps fit your shopping habits, which require planning, which accumulate rewards slowly and which offer actual cash withdrawals.
Then, when you need to stretch your money, you're not starting from scratch.
Stop Guessing. Know Your Number.
For years, I've used a simple paycheck-to-paycheck tracker to answer one important question:
How much money do I actually need to make it from this paycheck to the next?
It starts with what's coming in, what's going out and whether there's a gap.
When I had a gap, that number became my target. Instead of simply feeling short, I could decide how much additional money I needed to generate through cash back, side gigs or other sources.
I've turned that approach into the Everyday Werk Cash Gap Tracker so you can do the same.
Coming soon: Get the free Cash Gap Tracker for Everyday Werk subscribers.
More Than $1,600 Later
I joined Ibotta in 2015.
I reached its $1,000 Club.
Then its $1.5K Club.
And today, my lifetime earnings are more than $1,600.
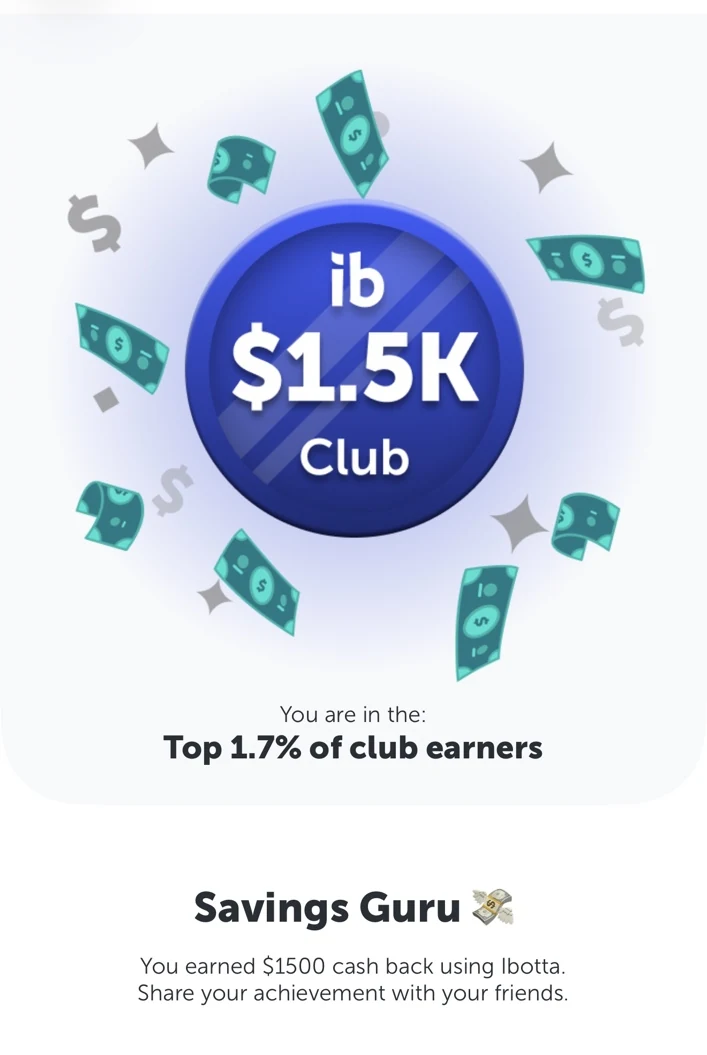
That doesn't mean everyone will earn what I have. My total reflects years of shopping patterns, available offers and how consistently I've used the app.
But it demonstrates something I believe strongly:
Small amounts of recovered money can become meaningful when you stop dismissing them.
Bonuses Can Help—But Don't Chase Them
I've taken advantage of Ibotta bonuses when the requirements aligned with purchases I already needed to make.
But I don't want a $5 bonus badly enough to buy $20 worth of products I don't need.
The goal isn't to complete the game.
The goal is to keep more value from spending that was already going to happen.
WATCH OUT: I Learned This Ibotta Rule the Hard Way
This is the part of my Ibotta story I wish I didn't have.
After a death in my family, cash-back apps were understandably nowhere near the top of my priority list.
I stopped paying attention to Ibotta for a long period.
What I didn't fully appreciate at the time was its inactivity policy.
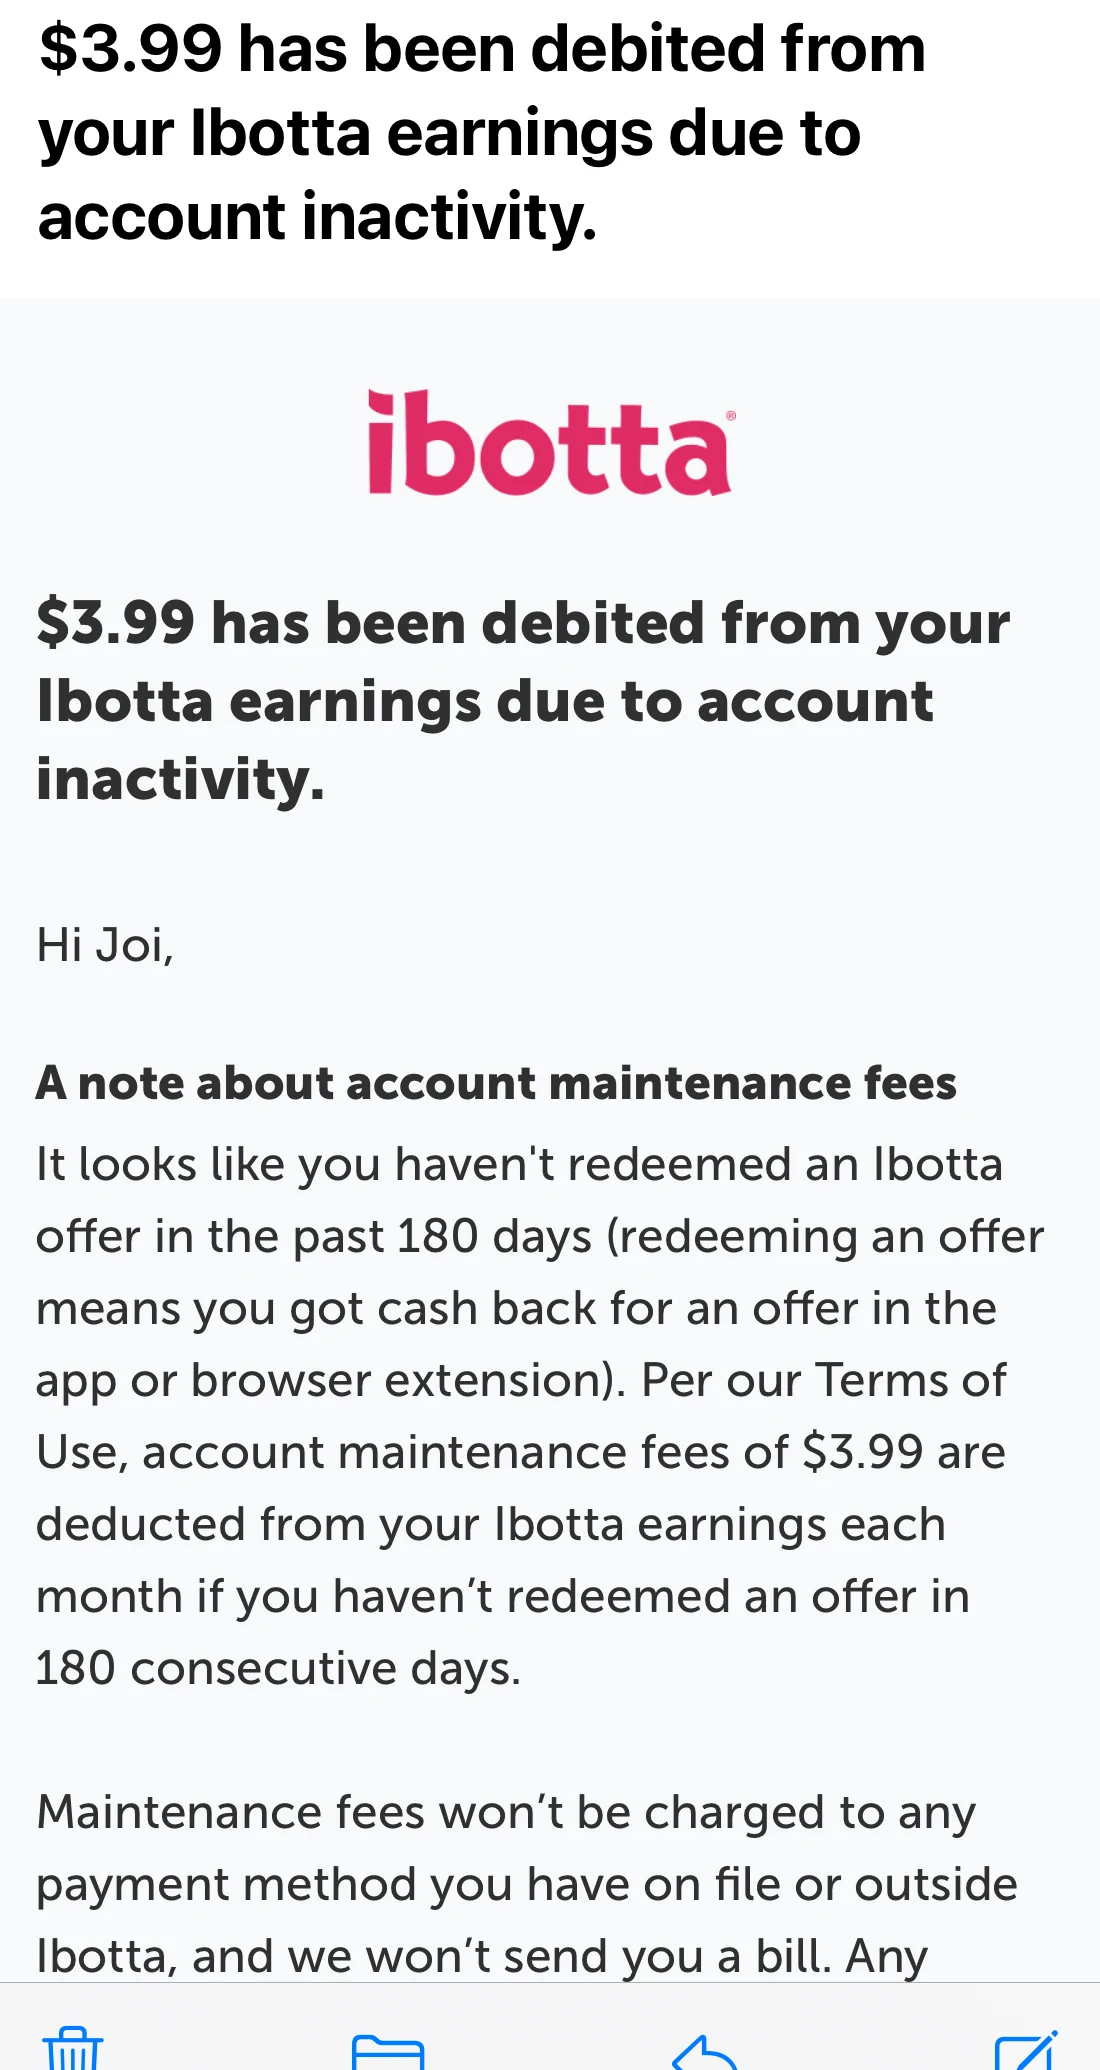
When I returned, I discovered that maintenance fees had been deducted from my accumulated earnings until eventually there was nothing left.
I learned that lesson the expensive way.
Under Ibotta's current policy, an account with a balance and no qualifying activity for at least 180 days may have $3.99 deducted from its earnings every 30 days while it remains inactive. Ibotta says those deductions come from the app balance—not your personal bank account.
WERK NOTE
If you've reached the withdrawal threshold and don't have a specific reason to leave the money in the app, consider cashing out rather than allowing it to sit indefinitely.
And make sure you understand what Ibotta counts as qualifying account activity. Simply opening the app isn't the same as completing an eligible redemption.
Don't Just Cash Out. Give the Money a Job.
Suppose you cash out $20.
What happens next?
If it disappears into your regular checking account and gets absorbed into everything else, you may never feel like you accomplished anything.
Instead, give recovered money a destination.
Maybe it's an emergency cushion, an extra debt payment, a vacation fund, holiday spending or simply intentional fun money.
You could even create a separate savings bucket.
Cash out $20? Move $20.
Another app gives you $10? Add $10.
A side gig produces $75? Decide what job that money has.
Then look at the total six or twelve months later.
That's the bigger Everyday Werk principle:
Bridge the gap when you need to. Build the cushion when you don't.
Cash-back apps aren't a substitute for adequate income or emergency savings. But they can help you build the habit of recovering value, keeping it and using it intentionally.
Ibotta Pros and Cons
| What I Like | What I'd Watch |
|---|---|
| Actual cash-back earnings | $20 minimum withdrawal |
| Bank and PayPal withdrawal options | Requires planning for many offers |
| Can fit purchases you're already making | Offers won't always match your shopping list |
| In-store and online opportunities | Coupon restrictions vary |
| Bonuses can increase earnings | Chasing bonuses can encourage unnecessary spending |
| More than a decade of value in my experience | Inactivity fees can erode unused earnings |
Is Ibotta Worth It in 2026?
For me, I continue using Ibotta because it has a specific job in my money system.
I don't use it to convince myself to shop.
I don't assume every offer is a good deal.
And I certainly don't expect it to solve a major income problem.
I use it to recover some of the money from spending that was already going to happen.
After more than ten years and over $1,600 in lifetime cash back, that still has value to me.
My approach is simple:
Plan what I need. Check whether Ibotta can improve the purchase. Shop normally. Claim the cash back I'm eligible to receive. Cash out. Give the money a job.
Because you're already spending it.
You might as well make the spend WERK for you.
Frequently Asked Questions
Is Ibotta legitimate?
Ibotta is an established cash-back platform. I've personally used it since November 2015 and earned more than $1,600 over that period. Your earnings will depend on your purchases, available offers and activity.
How much do you need to cash out?
The minimum is $20 in eligible earnings. You must also meet Ibotta's additional withdrawal requirements.
How long does Ibotta take to pay?
Eligible purchases may post relatively quickly, but earning enough to reach the withdrawal threshold can take longer. Once eligible, payment timing depends on your withdrawal method.
Can I add an offer after shopping?
For some qualifying receipt submissions, you may be able to add eligible offers during the submission process. Check the retailer's instructions and receipt deadline.
Do Ibotta earnings expire?
The important issue is its inactivity-fee policy. After at least 180 days without qualifying activity, Ibotta may deduct $3.99 from an existing balance every 30 days while the account remains inactive.
Can I use coupons with Ibotta?
Sometimes. Rules vary by retailer and offer. Check the terms before assuming you can combine a manufacturer coupon with an Ibotta rebate.
Ready to try Ibotta? Download it from the official website, the Apple App Store or Google Play.
Editorial disclosure: This review reflects my personal experience. Any future referral or affiliate links will be clearly disclosed.